Mastodon Cancel Infinity

Monday, June 29, 2015

What is the Conflict Between Uninformed Priors and Gambling?

Via Noah Smith at Twitter, Deborah G. Mayo asks “What do hard-nosed Bayesians like Gelman really mean by posterior probability?” In reading the piece, I grew concerned that Mayo left out something important to Andrew Gelman.

The following example pretty well describes the issue at hand.

Suppose I ask you show me a coin from your pocket and then ask you to flip it once. If it comes up heads, are you now willing to stake \$3 for a chance to win \$4 if among the next 1,000 flips at least 500 are heads? Or do you still think the coin is fair and you expect this bet on average would lose you \$1?
This illustrates the difference between an uninformed prior and a strong prior. If you began with a very weak prior– that is, prior to flipping the coin you believed the bias of the coin was equally likely to be always coming up heads as always coming up tails as anywhere in between– then you might take the bet. If on the other hand your experience is such that you do not frequently wind up with heavily biased coins in your own pocket then you might not think much of that first coin flip.

I think Gelman’s point is that however useful you may find it to employ an uninformative prior to communicate science, that does not mean your personal prior is necessarily uninformed. Therefore you might not make personal decisions based on a posterior derived from an uniformed prior– or, presumably, any prior much different than your own.

I am of two minds about the implications for reporting. My instinct is that biases should be made clear and so perhaps personal priors should be used in place of uniformed. On the other hand, a strong prior may greatly reduce the power of the study. If I believe that 999 of 1,000 coins yield tails 99 times out of 100, then a single flip of heads will do little to convince me that the coin is not biased toward tails. Is it really useful for me to report that I believe the coin is almost certainly biased toward tails? Is that science or opinion? It seems therefore that the likelihood– rather than the posterior– is the important scientific result of the study. In this case, the likelihood is identical to the posterior derived from the uniform prior, so there is no choice between these two.

To take an example from my own research, consider the audit of the April 14, 2013 Venezuelan election. There, a very extensive audit– 53 percent of more than 39,000 voting machines– turned up zero discrepancies between the numbers on the machines and paper ballots counted by hand. What conclusions may be drawn from this result? If you have uninformed priors, this seems overwhelmingly to suggest that the election was free of any meaningful audit-detectable fraud. If you believe strongly that the election results were fraudulent in a manner detectable by the audit, then it seems more sensible that the audit itself was a fraud. That is, your conclusion respecting the election result depends on your priors regarding possible fraud in the audit as well as the election. Scientifically, the important conclusion is that the audit results were not consistent with detectable fraud.1

Coming back to the original posts, then, it seems to me that Mayo missed Gelman’s point that priors do matter. I think Gelman is suggesting that relatively uninformed priors are reasonable for the basis of scientific reporting; in going beyond a study the reader must construct their own posteriors. To whatever extent possible, apply your Bayesian inference to your own priors rather than allowing someone else to insert their own.


1 To the point that a full audit of all voting machines would change nobody’s conclusions respecting the election results.↩

Thursday, April 9, 2015

Retirement Incomes are Falling for Many Americans, Despite What AEI Wants You to Think

Acknowledgement: I thank Andrew Biggs for his assistance in replicating his numbers.

In a new paper from the American Enterprise Institute, Andrew Biggs and Sylvester Schieber argue that workers retirements are more secure financially than some suggest. In part, they point to the ratio of household assets to wage earnings for those with heads aged 45-54. While their criticisms may have some validity, there are some significant omissions that cut the other way. On balance, it is likely that most households will rely more heavily on Social Security to support their retirements than in prior years.

According to the Survey of Consumer Finances, on average household wealth for the 45-54 age group fell from 5.8 years of wages in 2007 to 4.7 in 2013. Household wealth here— consistent with Biggs and Schieber—includes the value of a home and any other real estate, plus financial wealth. Mortgages and other debt are subtracted to get this number, as seen in Figure 1.

Figure 1: Biggs and Schieber’s mean assets relative to household wage income: all 45-54 year old householders
Source: Survey of Consumer Finances and author’s calculations

At 5 percent interest, this wealth could replace only 23.4 percent of current wage income compared to 28.8 percent in 2007.1

Trends in the Labor Force 1999-2014: Seniors Increase Participation, Younger Workers Withdraw

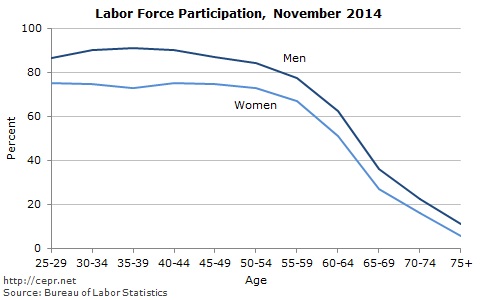
In early 2000, the civilian labor force participation rate peaked at a post-war high of 67.3 percent of the population aged 16 and over. Despite flattening out in the latter part of the decade at about 66 percent, participation rates never recovered and have steadily fallen since the onset of the Great Recession. At 62.8 percent as of November 2014, labor force participation is now at its lowest level since 1978.

Some of this fall is clearly demographic. Workers are much less likely to have or search for a job once near or past retirement age, as seen in Figure 1.

Figure 1:


Thus, the aging of the baby boom generation has reduced the size of the labor force. On the other hand, retirement-age workers are participating at a much higher rate than before. In small part, this is because baby-boomers have reduced the average age of those 65 and over. However, labor force participation in the older population has been rising for some time, as seen in Figure 2.

Figure 2:


Tuesday, March 3, 2015

“Mumbo-Jumbo” Mumbo-Jumbo

Today, Cato’s Alan Reynolds took a few bizarre shots from the pages of the Wall Street Journal. In particular, Reynolds it calls “far-fetched” that incomes of the middle class have stagnated for decades.

First, he asserts “The average income for the bottom 90% is not a decent proxy for the median nor even a decent measure of household income." This is clearly indefensible as a check of the numbers at Reynolds’ source demonstrates. Here, we see the average of the bottom 90 percent and the median compared for both before-tax and after-tax household income.

(Source)

Over Reynolds’ chosen 1984-2007 period, median before-tax income fell 0.05 percent per year relative to the bottom 90 percent and median after-tax income rose less than 0.01 percent per year relative to the bottom 90 percent. Obviously, such differences are in no way meaningful.

Next, Reynolds argues that median after-tax (and transfer) measures better describe the evolution of middle-class incomes than does pre-tax and transfer “market income.” However, the comparatively higher rate of growth in after-tax income simply reflects the government attempting to compensate households for the broad stagnation of income. If the median household is better off in 2007 than 23 years prior it is because we have recognized that wages have fallen and households have had to work much more to maintain a modest 0.5 percent annual increase in pre-tax income. We have increased transfers and cut taxes in order to help those households to share in the increased productivity of the economy.

It is also worth noting that much of the increased transfers which make up the wedge between market and pre-tax incomes have come as a result of a broken health-care system. The government now pays health providers considerably more and yet life expectancy for those in the bottom half of the income distribution has grown so slowly that such workers may enjoy shorter– not longer– retirements. It is not so obvious that such increases in payments contribute to growth in household income.

It is no surprise then that real per-person consumption has grown faster than median pre-tax household income. Not only does this conflate the median with the overall average— it ignores that household savings rates have declined considerably over the decades in question. In 1989, the median net wealth of households headed by someone aged 45-54 was \$177,300 compared to only \$105,400 in 2013. Even that does not consider the simultaneous decline in defined-benefit pensions held by such households.

The middle class may still appear middle class because households have dedicated more time to work, received increased assistance from the government, and accumulated considerably less wealth than the previous generations; such measures merely hide the obvious stagnation.

Wednesday, December 3, 2014

Thomas Piketty and the evolution of capital

Having finally read through Capital in the 21st Century (and spent considerable time with the supplied data) I find many critiques of Thomas Piketty very odd. Part of this is that Piketty (to my mind, anyway) tries very hard to take care with his words. Thus, I get annoyed when I see Branko Milanovic write
Just as a reminder: as we all know by now, $r>g$ implies that the stock of capital is increasing faster than net income.
We know this? Milanovic of course does not. Indeed, his post outlines a case where it may not be true. What irks me is that Milanovic seems to believe it to be generally understood. Frankly, I am not clear if Milanovic is critiquing Piketty or the public. With that in mind, let us begin to review the basic analytical framework presented in Capital.

Piketty defines “capital” or “wealth” as the market value of productive physical capital and net financial assets owned by households and government. Piketty’s capital includes residential real estate, but not consumer durables. It includes corporate-owned equipment through direct stock holdings of households and indirect holdings through pensions and other savings vehicles. Capital also includes holdings of foreign assets net of liabilities. Piketty divides the total value by national income (net of capital depreciation) and expresses the result, $\beta$, in terms of years.

Now define (net) savings as net investment and net acquisition of foreign financial assets so as to equal the change in real wealth, apart from miscellaneous volume adjustments and inflation-adjusted capital gains. If we presently assume these are zero, then the capital-income ratio must evolve as $$ \beta_t=\frac{\beta_{t-1}+s_{t-1}}{1+g_t} $$ where $s_t$ is net savings as a share of net income in period $t$ and $g_t$ is the real (inflation-adjusted) growth rate of net income from period $t-1$ to $t$. Note that regardless of $\beta_{t-1}$ or $g_t$, if $s_{t-1} < g_t\beta_{t-1}$, then $$ \beta_t<\frac{\beta_{t-1}+g_t\beta_{t-1}}{1+g_t}=\beta_{t-1} $$ Thus, Piketty’s “stock of capital is increasing faster than net income” if and only if there is sufficient net savings irrespective of the rate of return on capital.

What then is the significance of $r>g$? Stay tuned...

Tuesday, December 2, 2014

Mitchell finally notices the obvious

Cato’s Daniel J. Mitchell finally takes note of years of flat government spending. Months ago, I suggested this ought to make him “love President Obama” but he is still keeping any love to himself. Instead, Mitchell merely speculates this is all ”very depressing“ for the President.

On the other hand, he damns Obama with faint praise.
And even though we haven’t had impressive growth during the Obama years, there have been modest increases in both nominal GDP as well as inflation-adjusted (real) GDP.
Yes. There has been growth. Whee. Give it another six years and he may even consider the connection between the government’s withdrawal of demand and the piss-poor growth of the economy.

Wednesday, September 10, 2014

Waste is waste is waste

The fact that we are able to meet the nutritional needs of a great many more people does not mean we have no need for sewage systems and water treatment plants to deal with the slough of disease-spreading shit running down our streets.

Likewise, increased carbon dioxide concentration in the atmosphere is no cause for celebration.

That is all.